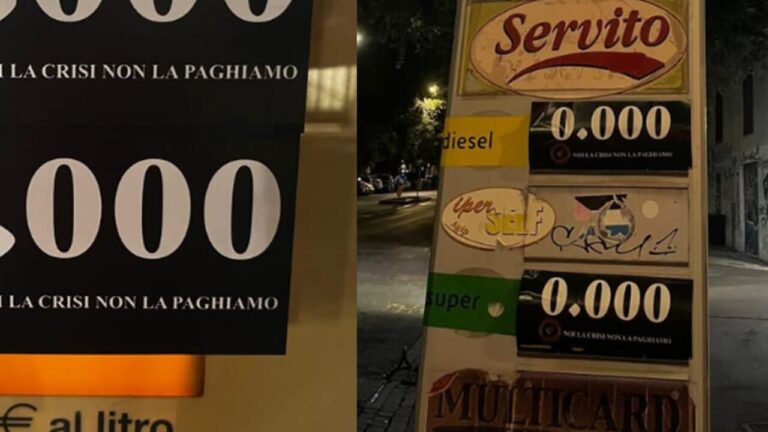
The new energy surge risks changing the economic scenario again in the autumn. Brent surpassed 107 dollars per barrel, while European TTF gas reached around 84 euros per megawatt hour, the highest level since January 2023. And this time the problem does not just concern petrol and bills: if oil and gas remain at these levels long enough, the effects will progressively arrive on the prices of goods, on businesses, on interest rates and finally on growth.
The new tensions in the Middle East are driving prices above all. Attacks on Saudi infrastructure, the difficulties of the route through the Strait of Hormuz and the pressure on the Bab el-Mandeb are reducing the amount of oil available and, above all, exploding the costs of transporting it. The International Energy Agency has further worsened its estimates for the global supply of crude oil in 2026, while the inventories accumulated in previous months are decreasing.
Worse than the worst projections
To give an idea of how worrying the situation is, here’s a detail: the markets have entered, at least temporarily, into territory worse than what the European Central Bank defined as an adverse scenario just a few weeks ago.
In the September projections, the ECB assumed, in the central scenario, around 88 dollars per barrel for oil and 60 euros/MWh for gas in the fourth quarter of 2026. The scenario defined as “adverse” rose to 99 dollars and 77 euros respectively. The extreme one instead reached 132 dollars for oil and 130 euros for gas. Today Brent is above 107 dollars and gas contracts for delivery in December exceed 83 euros.
And it is above all gas that worries the ECB. Isabel Schnabel explained that the problem no longer concerns only crude oil, but also diesel, natural gas and electricity. European stocks also arrived on the eve of winter in decidedly less reassuring conditions than in recent years: at the beginning of September, European Union stocks were only around 66% full, the lowest level in the last fifteen years for this period.
First consequence: inflation starts to rise again
The first victim will therefore be disinflation. The ECB already expects eurozone inflation to peak at 3.6% in the last quarter of 2026, versus its target of 2%.
But the real problem will come later. Energy enters the production and transportation costs of practically any product: from food to chemicals, from building materials to logistics services. If oil and gas remain expensive for a few months, companies gradually begin to transfer part of the increased costs onto the price lists.
In the ECB’s central scenario, inflation should fall to 2.5% in 2027 and return to close to 2% thereafter. In the most extreme scenario, however, average inflation in 2027 would even reach 5.4%.
Second consequence: rates could rise further
Only a few months ago the question seemed to be when Frankfurt could start reducing the cost of borrowing again. Today the question is the opposite: how many more increases will be necessary? On September 10, the ECB already increased rates by 25 basis points, bringing the deposit rate to 2.5%, citing new inflationary pressures coming from the Middle East.
The markets are once again betting on further increases and several members of the ECB now see inflation risks clearly oriented towards the upside. For families and businesses it means more expensive variable mortgages, more expensive new loans and stricter conditions for those who have to invest.
The account for Italy
Italy is particularly exposed because it imports much of the energy it consumes and is still heavily dependent on gas to produce electricity.
Even before the latest acceleration in prices, the association of oil companies Unem estimated that in 2026 the Italian energy bill would rise towards 60 billion euros, approximately 8-9 billion more than in 2025.
Any further increase therefore means transferring more wealth abroad and worsening the trade balance. For energy-intensive companies it also means returning to compete with US or Asian competitors who, in many cases, pay much less for energy.
The risk is particularly evident for chemicals, steel, glass, ceramics, paper and fertilizers. But also for thousands of small companies, because the increase in electricity and transport ends up compressing margins while the cost of credit remains high.
From petrol to shopping: when will the increases arrive
On fuels the effect is almost immediate and is amplified at this stage by the high refining margins: the ECB underlines that diesel and other refined products have increased more than crude oil itself due to the lack of capacity and transport difficulties.
Fuels towards 2.5 euros per litre, the “invisible” cost of closed refineries: this is how Italy got into trouble
For gas and electricity, the times depend on the contract signed by the families and the methods for updating the offers. The effects on food and other goods normally take a few months, because they have to pass through the entire production and distribution chain.
The real risk is stagflation
For now, the European economy is holding up better than expected. The ECB estimates growth of 0.9% in 2026 and 1.4% in 2027, while Giorgia Meloni has indicated growth of around 1% for Italy this year. But it all depends on the duration of the shock.
If oil and gas fall rapidly, the effect on the economy could remain relatively small. If, however, the Gulf crisis were to continue throughout the winter, the risk would be what economists fear most: higher inflation together with lower growth. The ECB itself has tried to quantify it. In its extreme scenario, with oil around $130 and gas near €130/MWh, Eurozone growth in 2027 would plummet to 0.4%, while inflation would rise to 5.4%. In the central scenario, growth of 1.4% and inflation of 2.5% are forecast respectively.
In other words, we are not yet in the worst case scenario. But the distance suddenly closed.
The next few weeks will therefore be decisive. The numbers to observe will not only be those of Brent. We will need to look above all at the price of gas, the filling of European storage, the flows through Hormuz and the Red Sea and the decisions of central banks. Because a new energy crisis is not only measured at the pump or on the bill: after a few months it ends up entering practically every item of the economy.
The result could be an autumn with already higher energy prices and a winter in which the increase begins to appear on the rest of the shopping cart.